China's AI basic data service market reached 6.262 billion yuan, with leading companies beginning to emerge – IDC – September 14, 2026.
As artificial intelligence transitions from "technological exploration" to "large-scale deployment," basic data services are no longer simply a labor-intensive industry, but rather a core infrastructure determining the upper limit of model performance. However, the market still faces many gaps in understanding regarding the value measurement standards, technological evolution paths, and business models of data services. To clarify the true level of the industry and guide enterprises in formulating sustainable data strategies, International Data Corporation (IDC) has, for the first time, conducted a systematic quantitative study of AI basic data services as an independent sector, and recently officially released the "China Artificial Intelligence Basic Data Services Market Research Report, 2025" . The report shows that the market size of China's AI basic data services reached RMB 6.262 billion in 2025 , a year-on-year increase of 27.8%, exceeding market expectations. The market size is projected to further grow to RMB 7.834 billion in 2026, with a compound annual growth rate (CAGR) of 19.6% from 2025 to 2030.
Despite downward pressure on the overall economic environment, the AI basic data services market has bucked the trend and grown strongly, driven by the robust development of artificial intelligence. The customer base has expanded from traditional AI companies to a wider range of sectors, including government, autonomous driving, and embodied intelligence. Data demand is being driven by the application of AI, shifting from consumer entertainment to scenarios that substantially improve productivity.
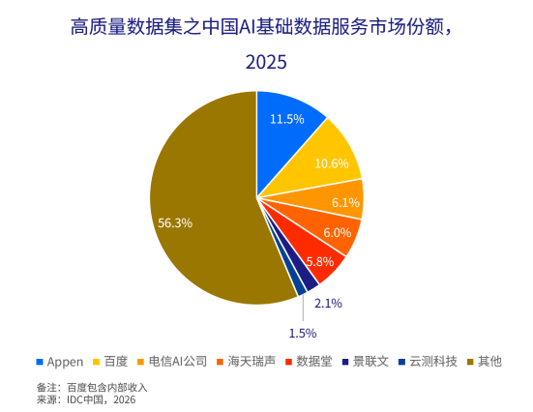
Market structure: The concentration of leading manufacturers remains low, while others account for over 56%.
In terms of the competitive landscape, the leading vendors in China's AI basic data service market in 2025 include Appen, Baidu, China Telecom, Haitian Ruisheng, DataTang, Jinglianwen, and Yuntest Technology. Appen holds the top position with an 11.5% market share, followed closely by Baidu with 10.6%. It's worth noting that the overall market concentration remains low, with other categories accounting for a significant 56.3%, indicating relatively low barriers to entry and a continued influx of vendors.
Leading vendors experienced faster-than-expected market growth, but their products lacked significant differentiation. Vendors primarily leveraged automated annotation tools to reduce annotation difficulty and costs, aiming to gain more market share. When selecting data service providers, clients placed greater emphasis on a vendor's past service experience, personnel costs, responsiveness to requests, and data acquisition capabilities.
To learn more, visit: www.idc.com